
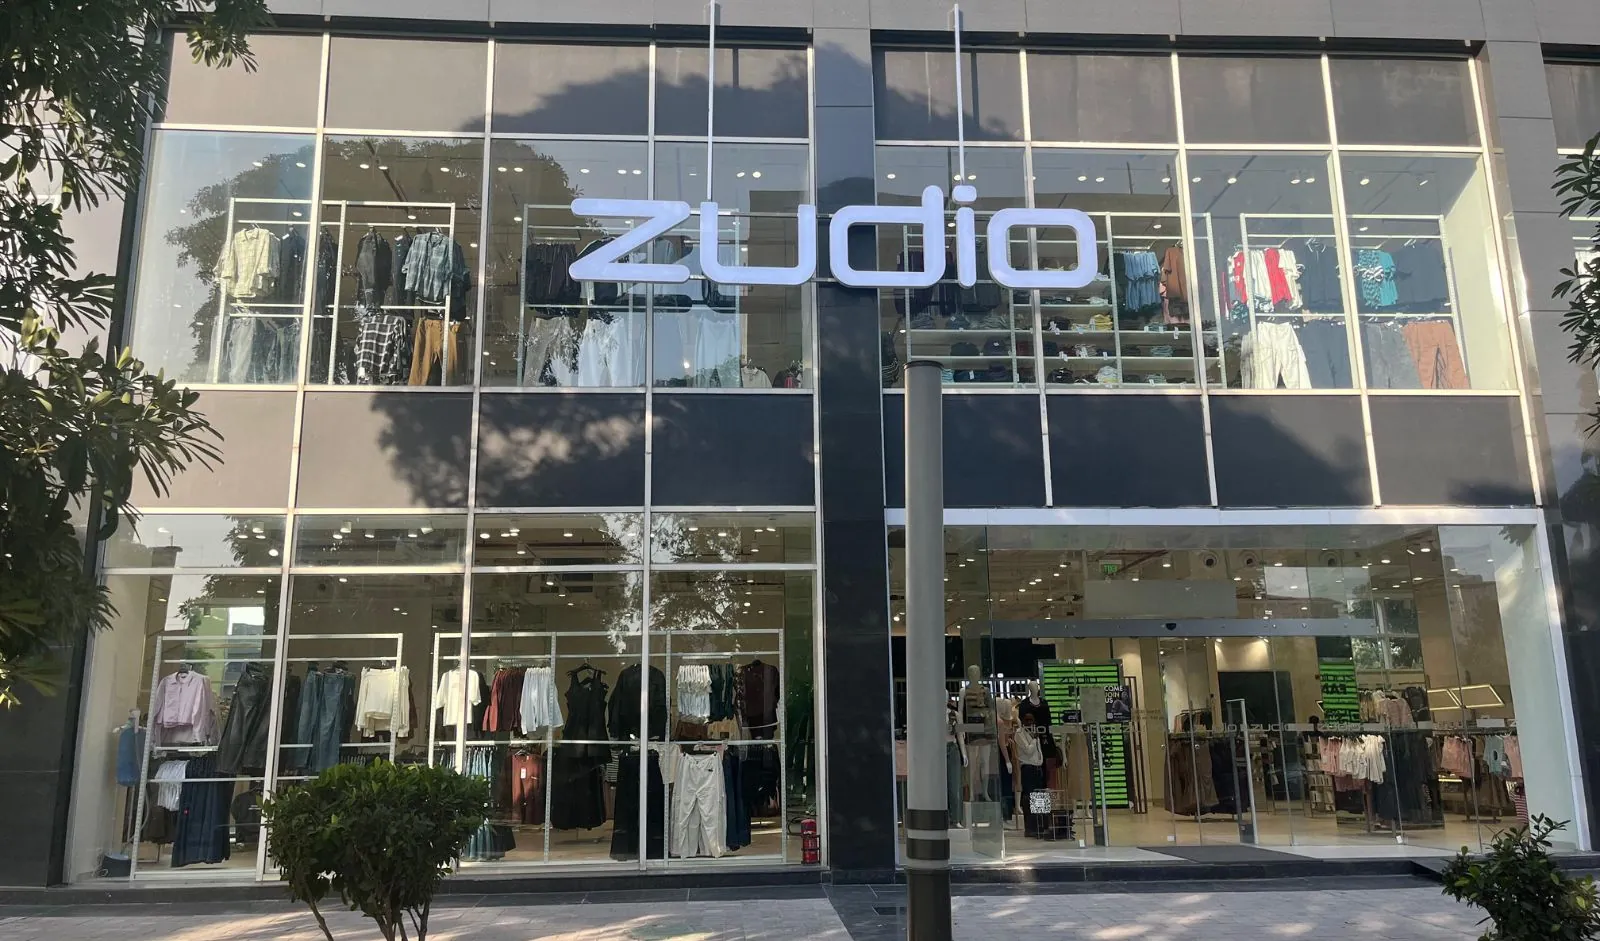
Trent Ltd. experienced a sharp double-digit stock decline in early July 2026. The cause was simple math meeting impossibly high standards. The retail parent of brands like Westside and Zudio delivered robust, high double-digit revenue expansion for its first quarter. But Wall Street expected more. Investors had priced the stock for absolute perfection, and when the company failed to clear those lofty growth forecasts, the market aggressively corrected the valuation.
How Retail Valuation Expectations Work
Share prices do not exist in a vacuum. They reflect what investors believe a company will do in the future. Heading into the Q1FY27 earnings update, Trent traded at premium multiples bordering on triple digits. That kind of pricing leaves virtually zero margin for error.
A standard retail business would celebrate the revenue jump Trent posted. The problem here is the expectations reset. A price-to-earnings multiple measures how much an investor is willing to pay today for a dollar of the company’s future profit. When that number approaches triple digits, the market is essentially pricing in years of uninterrupted, flawless execution. Because rapid expansion was deeply baked into the stock price, even a minor moderation in growth triggered a heavy sell-off. Investors quickly reduced the premium they were willing to pay for future earnings.
Who Feels the Impact of the Sell-Off
Institutional shareholders and retail investors are now forced to re-evaluate their long-term thesis on the stock. For months, market attention was locked onto headline revenue figures. Now, the focus has abruptly shifted to underlying sales quality and store productivity.
Analysts from Citi pointed directly to a double-digit decline in average revenue per square foot during the quarter. That specific metric spooks investors. It suggests that while the company is generating more money overall, individual stores are becoming less efficient at moving inventory.
A Real-World Look at Zudio’s Trajectory
Zudio operates as the primary growth engine for the entire enterprise. Its footprint currently dwarfs the older Westside brand by a nearly three-to-one margin. Investors expect this value-fashion segment to scale aggressively across new geographies.
During the June quarter, the company added a relatively modest batch of new retail locations on a net basis. Some market observers considered this pace too slow. And then there is the cannibalization risk. Analysts estimated a mid-single-digit drop in per-store revenue, raising fears that new Zudio outlets are opening too close to existing ones. They end up eating into each other’s foot traffic, pushing out the time it takes for a new location to mature.
Value fashion requires immense volume to work. Profit margins on individual items are razor-thin, meaning the business relies on high foot traffic and rapid inventory turnover. When per-store revenue dips, those thin margins come under immediate pressure. Sure, the June quarter is historically the weakest period for retail store additions. But a market paying peak prices rarely cares about seasonal context.
Key Considerations for Market Observers
The business update fractured Wall Street consensus. Major financial institutions issued starkly divided ratings on where the stock goes next.
Analysts at Bernstein maintained an ‘Outperform’ rating. They looked past the slow start to the year and expressed confidence in the company hitting its full-year expansion targets. They see the dip as a temporary speed bump rather than a structural failure.
Morgan Stanley and Citi took much more cautious positions. Morgan Stanley analysts noted that the stock’s substantial prior rally inherently limited its near-term upside. Citi reiterated a ‘Sell’ rating. They leaned heavily on the deteriorating store productivity metrics and the escalating competition within the broader apparel sector.
Key Takeaways
- Stock prices driven by exceptionally high multiples are vulnerable to steep corrections if quarterly performance falls even slightly below aggressive market estimates.
- Rapid physical footprint expansion eventually forces analysts to prioritize per-store efficiency metrics over broad, top-line revenue growth.
- Differing institutional perspectives often emerge during a correction, highlighting the tension between long-term brand confidence and immediate operational headwinds.