
A loan-to-buy clause embeds a future permanent transfer agreement into a temporary player arrangement. A standard loan allows a football player to temporarily play for a different club to gain first-team experience, cover immediate squad injuries, or reduce a parent team’s wage bill. The foundational definition of sports loans establishes this temporary nature. A buy clause changes the legal dynamic entirely.
Instead of merely borrowing a player for a single season, the borrowing team secures the right—or takes on a strict mandate—to purchase the player’s full rights for a pre-agreed fee when the temporary spell concludes. Players must agree to these terms before the initial move happens. When the transfer is negotiated, the player typically signs a temporary agreement alongside a pre-agreed permanent contract of employment that instantly activates if the purchasing club triggers the buying clause.
How Transfer Market Buy Clauses Work
Clubs structure these deals in distinct ways depending on who carries the financial risk. The legal mechanics break down into three primary categories.
- The Option to Buy: This clause grants the borrowing club the discretionary right to purchase the player’s full rights for a set fee at the end of the loan. It functions as a risk-free trial period. The buying club assesses the player’s form, physical fitness, and tactical fit before committing to a permanent transfer. If the player underperforms, the club simply returns them to their parent team without financial penalty.
- The Obligation to Buy: This imposes a binding contractual commitment on the borrowing club. They must purchase the player permanently once the loan period concludes. The financial risk sits entirely with the buying club. They must fulfill the obligation and pay the transfer fee regardless of whether the loan spell goes well or the player suffers a severe injury.
- Conditional Triggers: Obligations frequently tie into specific performance metrics. If agreed conditions are met on the pitch, the permanent transfer automatically triggers. Common milestones include a player making a minimum number of starting appearances or the borrowing club achieving promotion to a higher domestic league.
Why Teams Use Deferred Payment Structures
Accounting flexibility drives the popularity of obligations to buy. By structuring a permanent transfer as an initial loan, the buying club can defer the official transfer fee to the following financial year. They push the associated amortization down the road. This strategy helps teams manage Financial Fair Play (FFP) regulations, allowing them to sign immediate reinforcements without breaching current seasonal spending limits.
Budget optimization plays a massive role for sporting directors. The structure allows clubs to manage cash flow by spreading large transfer fees across multiple accounting periods. You see this heavily in Italian football. The prestito oneroso con obbligo di riscatto (paid loan with an obligation to buy) eases financial pressure during a single summer window. You can read more about the Italian origin of the structure and how financial risk transfers fully to the buyer.
Major leagues around the world apply these rules to balance their books. An explainer on how global clubs utilize loan wage splits and buy clauses highlights the financial gymnastics teams perform to stay compliant. While borrowing clubs prefer options for flexibility, selling clubs generally demand obligations. Even if tied to conditional milestones, an obligation guarantees a future financial return and permanently removes the player from the parent club’s wage budget. This creates distinct strategic financial benefits for clubs and the agents who broker the deals.
Famous Examples from Major Transfer Windows
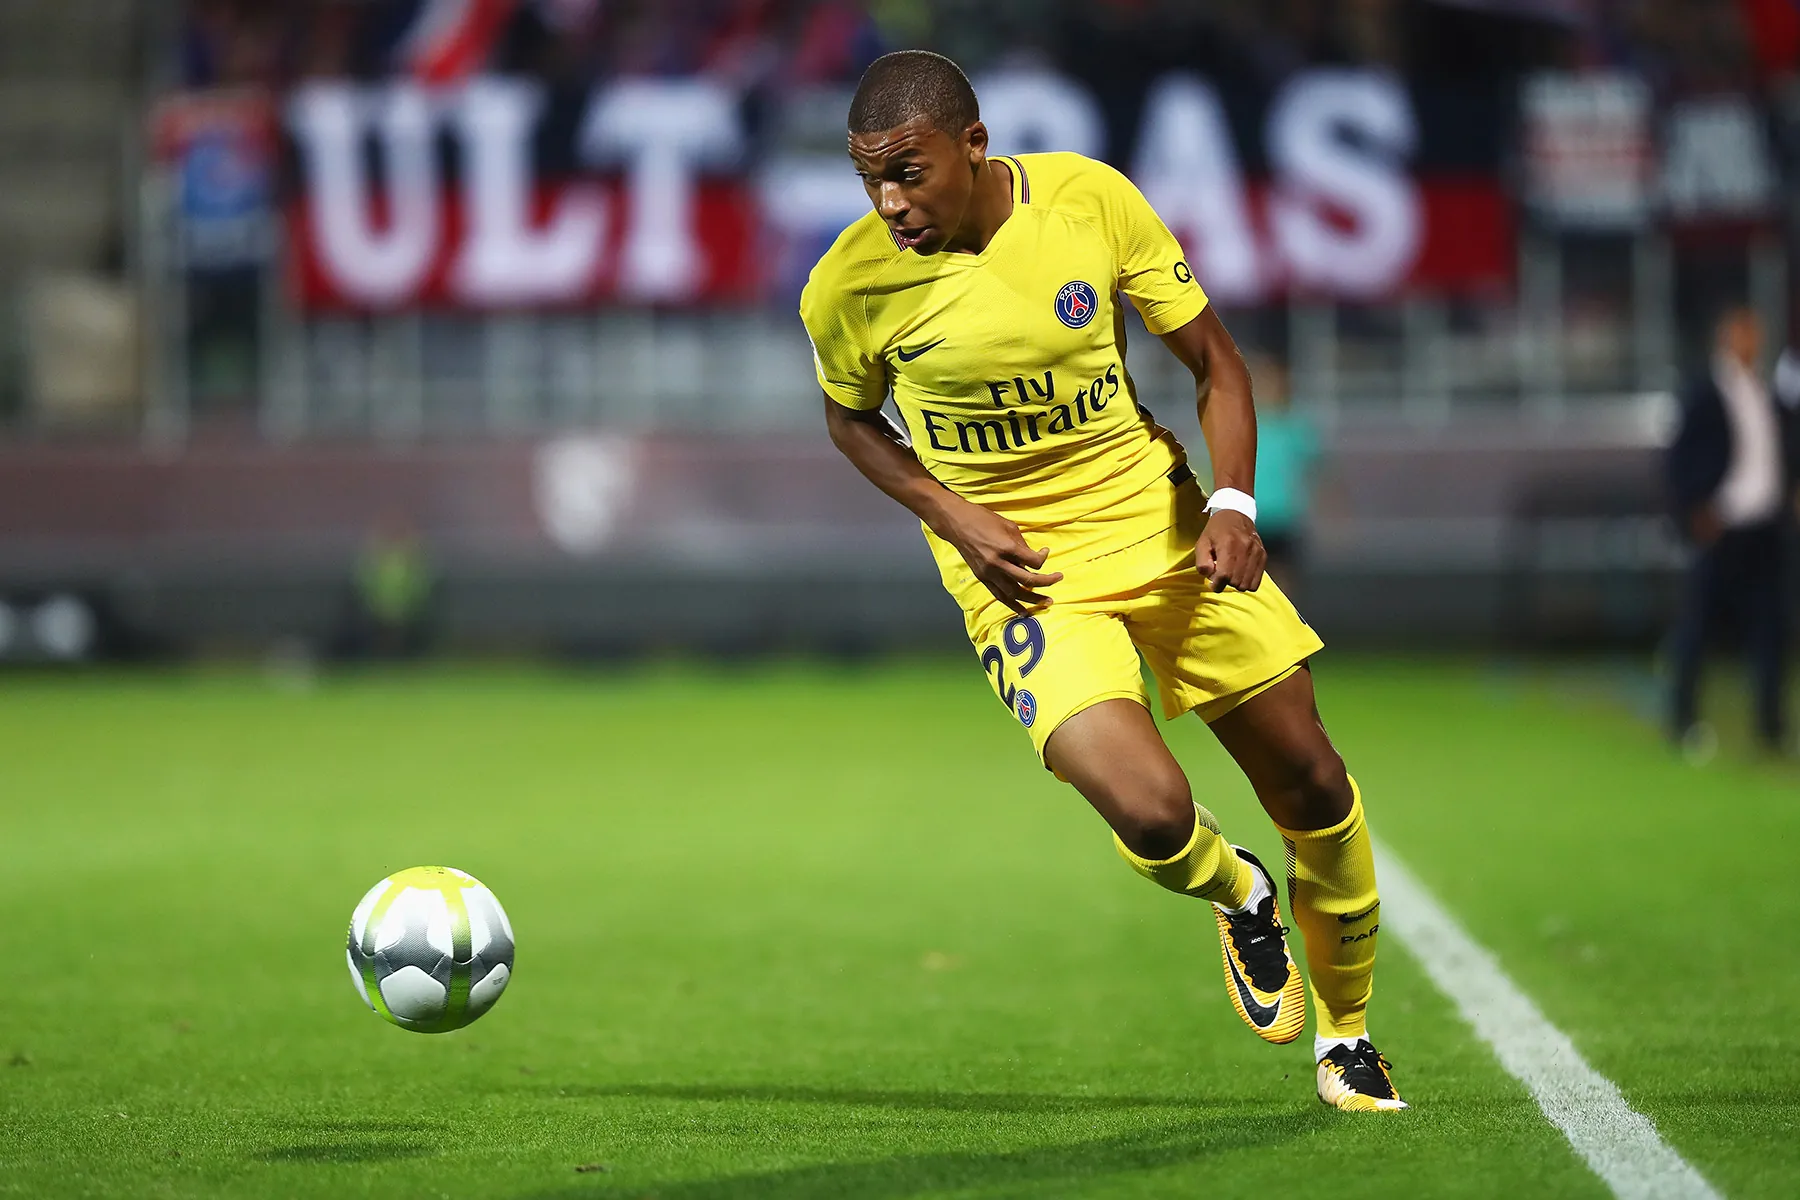
Paris Saint-Germain executed the most famous use of this financial structure in 2017. PSG signed forward Kylian Mbappé from AS Monaco on an initial loan with an obligation to buy for €180 million. The club spent €222 million on Neymar earlier that same summer. To prevent the massive Mbappé fee from hitting their accounts simultaneously, the obligation conditionally triggered only if PSG avoided relegation from Ligue 1. That was a virtual certainty that legally satisfied accounting regulations.
The Mbappé deal shifted how teams viewed temporary transfers. It highlighted the potential for circumventing financial rules, a trend outlined in a 2022 academic analysis by Brown regarding vicarious liability and sporting loans.
In 2023, Wolverhampton Wanderers agreed to a loan with an obligation to buy forward Matheus Cunha from Atletico Madrid for €50 million. The contractual condition to trigger the permanent transfer was highly achievable. Cunha only needed to play three matches for the English club to activate the clause.
Not every deal guarantees a permanent move. In 2015, Chelsea signed Radamel Falcao from AS Monaco on a temporary basis with a pure Option to Buy. Official contract documents revealed the contract stipulated a €50 million fee if Chelsea exercised the option, at which point Falcao would sign a newly agreed permanent contract. Chelsea ultimately declined to trigger the clause after a disappointing season.
Common Misconceptions About the Loan Market
Casual fans often view temporary transfers strictly as player development tools. They assume parent clubs send young talent away purely to gain minutes on the pitch. The advent of lucrative loan-to-buy structures transformed the system into a complex, value-generating business strategy.
Critics argue that treating obligations to buy as “credit cards” artificially inflates player transfer values. The structure allows clubs that are already heavily leveraged to continue spending beyond their immediate liquid means. They acquire expensive players today and worry about the accounting bill tomorrow. Regulatory bodies continuously debate whether these structures allow wealthy clubs to ignore the spirit of financial sustainability initiatives.