
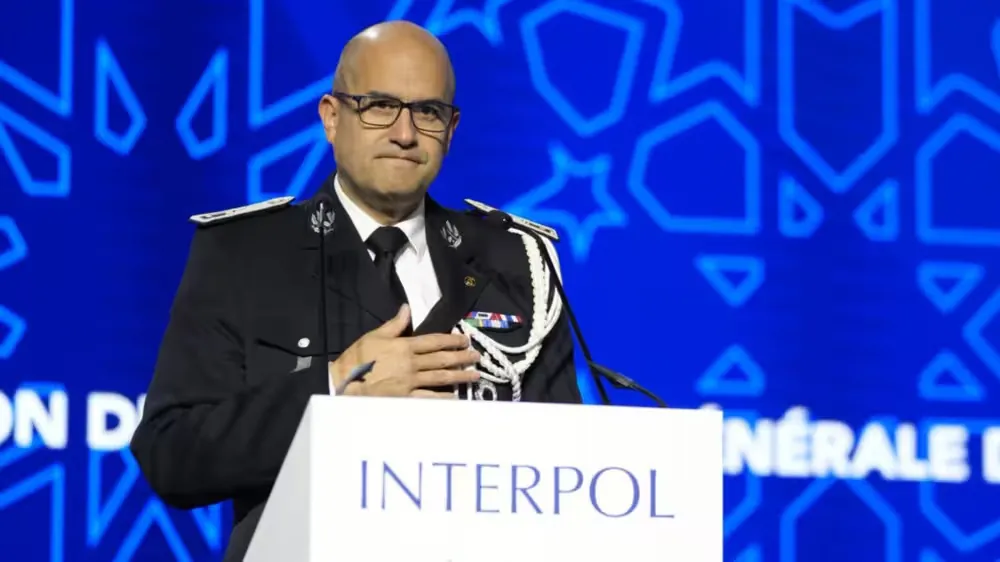
Interpol agents just concluded one of the largest financial sweeps in history. Between January 15 and April 30, 2026, a coordinated effort across 97 countries targeted the industrialized networks fueling global social engineering fraud. The operation resulted in 5,811 arrests and intercepted $293 million in illicit assets.
Right at the center of this enforcement action sits a 20-year-old suspect in Thailand. Thai police dismantled a criminal syndicate that funneled funds from online romance scams directly into digital assets. This single individual managed a digital wallet that processed more than $122.5 million in just 10 months.
The Cross-Chain Evasion Tactic
The technological arms race between law enforcement and cybercriminals is escalating rapidly. To move $122.5 million without triggering alarms, the perpetrators abandoned standard single-chain transactions. They used cross-chain token swaps to fragment the money trail.
This specific method exploits a known gap in global financial compliance. Cross-chain swaps allow launderers to bypass the Financial Action Task Force’s Recommendation 16, commonly known as the Travel Rule. The rule requires Virtual Asset Service Providers to transmit originator and beneficiary information alongside transactions. By jumping across different blockchains, the network bypassed standard monitoring tools entirely.
The scale of the infrastructure required to feed these decentralized off-ramps is highly complex. According to the official announcement detailing the results of Operation First Light 2026 and the Thai scammer’s $122.5 million wallet, modern laundering layers rely on tens of thousands of dedicated mule bank accounts.
How the Funnel Works
The transition from a romance scam victim’s bank account to an untraceable digital asset follows a strict, industrialized sequence:
- Extraction: Scammers manipulate victims into sending fiat currency to domestic mule accounts.
- Conversion: The funds are rapidly converted into stablecoins or primary cryptocurrencies through loosely regulated exchanges.
- Fragmentation: Operators execute cross-chain token swaps, converting the assets across multiple blockchains to break the forensic link.
- Off-Ramping: The untethered funds pool in a central wallet, like the one seized in Thailand, before final liquidation.
Japan Bridges Crypto and Consumer Credit
While Southeast Asia battles the weaponization of digital assets, Japan is rapidly normalizing them within traditional consumer finance. Major Japanese exchanges are pushing to integrate cryptocurrency directly with daily retail spending.
The rollout of new domestic credit products highlights this shift. The Binance Japan Card offers BNB cashback on regular purchases. Simultaneously, bitFlyer launched a Bitcoin rewards credit card. These products bridge the gap between speculative asset management and everyday commerce, treating crypto holdings similarly to traditional credit scores.
The Verdict
The cryptocurrency sector is currently operating in two radically different realities. In Japan, digital assets are becoming boring, integrated tools for earning credit card rewards. Across the rest of the region, decentralized networks provide cover for nine-figure fraud operations. Regulatory bodies face an immediate technical challenge: enforce the Travel Rule across cross-chain bridges, or watch industrialized scam networks continue to drain hundreds of millions through unmonitored swaps.