
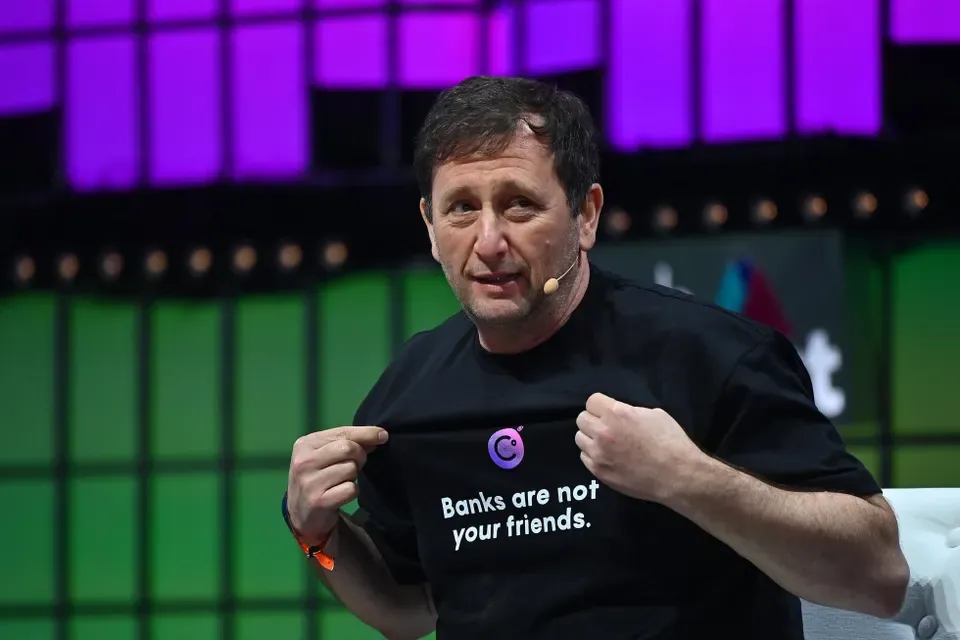
The Federal Trade Commission permanently banned the surviving leadership of the bankrupt Celsius Network from the financial services industry on Monday, concluding a multi-year pursuit with a $16.5 million settlement. Former CEO Alexander Mashinsky, alongside co-founders Shlomi Daniel Leon and Hanoch “Nuke” Goldstein, agreed to the final stipulated orders to resolve federal charges of deceiving 1.7 million retail consumers.
The July 20 settlement dictates a strict financial breakdown for the trio. Mashinsky owes $10 million, Leon will pay $4.1 million, and Goldstein faces a $2.4 million judgment. The agreement officially closes the FTC’s regulatory chapter on the 2022 collapse of the crypto lender, which froze customer accounts after operating with an unsustainable $1.2 billion balance sheet deficit.
What We Know
- Mashinsky and Leon are permanently banned from marketing or selling any deposit, exchange, or investment products.
- Goldstein received a slightly narrower restriction, permanently barring him from retail-facing cryptocurrency products.
- Both Mashinsky and Leon are explicitly prohibited from sharing nonpublic consumer data under the Gramm-Leach-Bliley Act.
Bankruptcy filings ultimately revealed a stark contrast between external marketing and internal actions. Weeks before freezing public withdrawals in the summer of 2022, the co-founders quietly cashed out tens of millions of dollars in cryptocurrency from their personal Celsius accounts. This occurred while the company continued to solicit funds by marketing the platform as a safer alternative to traditional banking, a strategy that eventually led to a massive $4.7 billion deficit.
The corporate entity of Celsius settled its own charges in July 2023. At that time, a suspended $4.7 billion judgment allowed the remaining company assets to flow back to consumers through bankruptcy proceedings. The three co-founders refused to agree to that initial resolution. That refusal forced the federal commission to push forward with individual federal court charges, according to the official FTC press release published after a unanimous commission vote.
Strict Liability Enforcement Sets a Permanent Retail Crypto Boundary
The sweeping bans handed down against the Celsius executive team establish a rigid enforcement precedent for digital asset platforms operating in the United States. Regulators are no longer stopping at corporate fines for bankrupt entities. By permanently excommunicating founders from the financial services industry, the FTC is signaling that executives who misrepresent liquidity or insurance protections will lose their ability to operate in any traditional or decentralized financial market.
This settlement operates concurrently with ongoing actions from the SEC, CFTC, and the Department of Justice. Mashinsky continues to face federal criminal fraud charges regarding his management of the platform, with decades in prison on the table if convicted.