
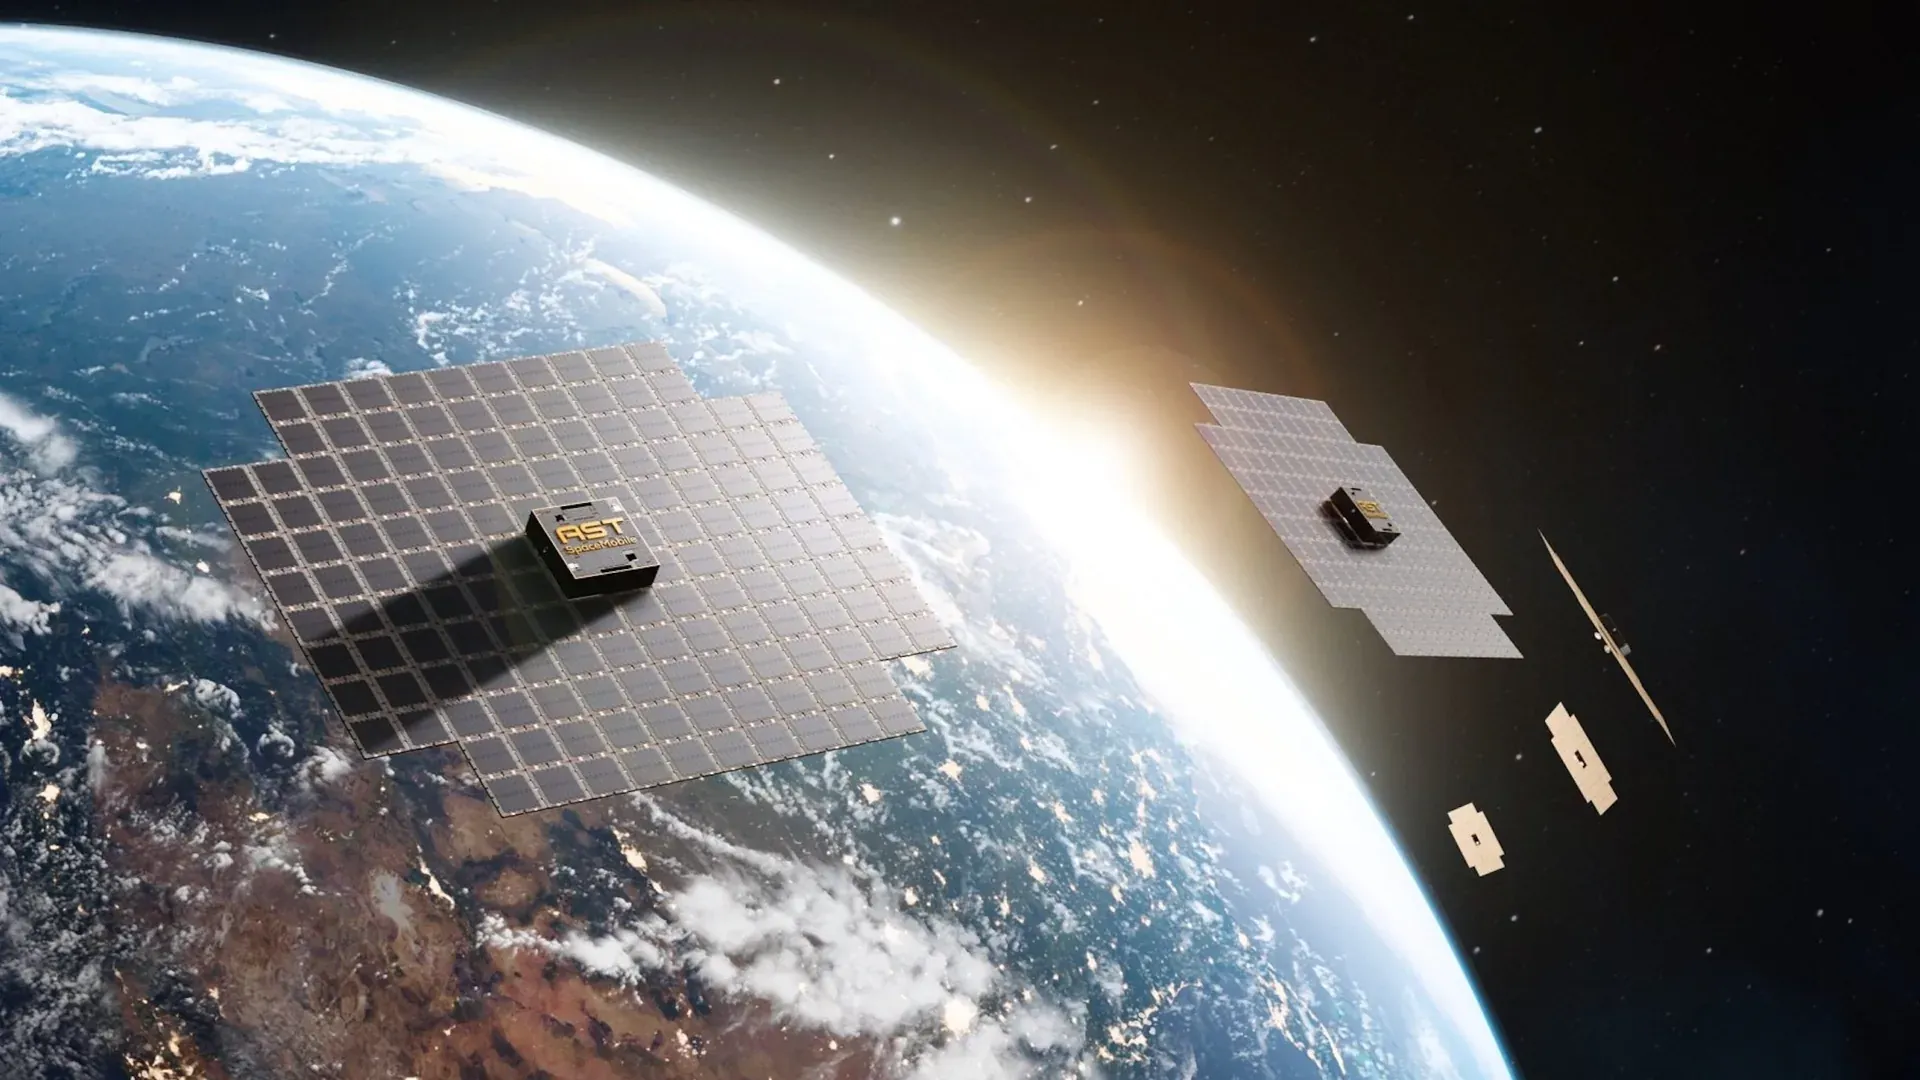
A historic influx of institutional capital into the commercial aerospace sector is fundamentally altering military defense procurement. Following SpaceX’s unprecedented $75 billion initial public offering in June, investment managers are aggressively pivoting toward smaller satellite and defense manufacturers. The shift is simultaneously driven by the ongoing U.S.-Iran conflict, where the unsustainable financial burden of intercepting low-cost drones has forced the U.S. military to prioritize cost-effective directed-energy weapons.
Portfolio manager Drew Cupps of Polen Capital identified six fast-growing, small-cap equities positioned at the center of this industry transformation. The analysis highlights AST SpaceMobile, Rocket Lab, Planet Labs, Kratos Defense & Security Solutions, nLight, and AeroVironment as prime beneficiaries of the expanding demand for global satellite communications and AI-driven data processing.
The market momentum for orbital infrastructure accelerated following the June 12 SpaceX IPO. Valued at $1.75 trillion, the market debut stands as the largest public offering in U.S. history. This liquidity event triggered a profound reallocation of assets, with institutional capital flooding into commercial space development firms. Competitors developing launch capabilities and satellite constellations, notably AST SpaceMobile and Rocket Lab, are experiencing heightened trading volume. Analysts tracking volatile price action note that smaller launch providers are capturing the overflow of investor interest from the SpaceX debut.
The Integration of Orbital Hardware and Artificial Intelligence
The integration of artificial intelligence with orbital networks is a core driver for these valuations. SpaceX’s $60 billion acquisition of the AI firm Cursor signaled a definitive industry pivot toward combining launch architecture with automated data processing capabilities. Planet Labs currently operates the largest imaging constellation in orbit, securing lucrative contracts with the U.S. Defense Department and foreign governments to track armored vehicles and maritime traffic.
On the tactical front, asymmetric warfare in the Middle East is accelerating defense hardware upgrades. Cupps specifically points to nLight and AeroVironment for their rapid advancement of directed-energy weapons. The U.S. military is actively seeking systems like nLight’s 70kW Hades units to intercept incoming threats at a fraction of the cost of traditional missile defense. According to a recent report by MarketWatch detailing the Polen Capital analysis, defense contractors like Kratos Defense are also establishing crucial partnerships, including a joint initiative with GE Aerospace to manufacture engines for small unmanned aerial vehicles.
How the U.S. Military Pivot Alters Defense Hardware Valuations
The transition from traditional kinetic interceptors to directed-energy weapons fundamentally changes the financial metrics of modern warfare. Traditional defense contractors have historically relied on the continuous resupply of high-cost consumable munitions. The U.S. military’s urgent requirement for laser-based interception systems threatens to disrupt that revenue model by offering an unlimited magazine capacity constrained only by electrical power generation.
This strategic pivot directly benefits companies specializing in power infrastructure and advanced optics. As the Department of Defense reallocates procurement budgets to counter asymmetrical drone tactics, smaller firms that can deliver deployable laser units and AI-integrated tracking software are capturing market share previously dominated by legacy aerospace conglomerates.