
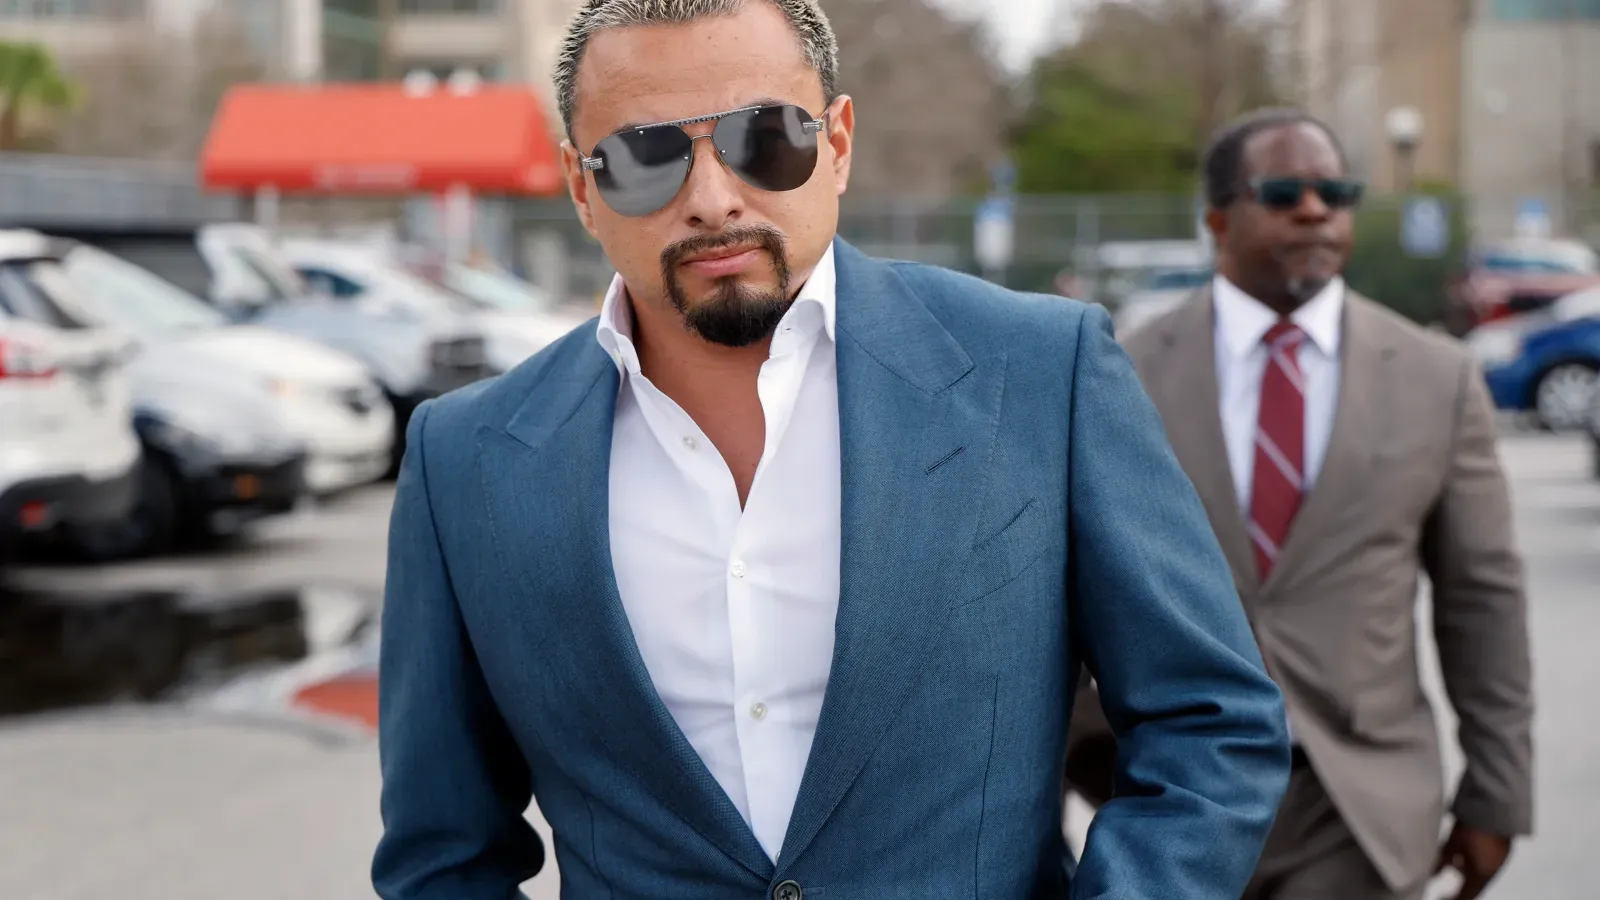
Christopher Delgado, the former head of Goliath Ventures, has surrendered to federal authorities following a months-long investigation into a massive cryptocurrency fraud. The move comes as federal regulators ramp up pressure on decentralized finance platforms amid a broader 2026 crackdown on digital asset misappropriation. Investigators allege the operation functioned as a classic Ponzi scheme that drained hundreds of millions from unsuspecting retail investors.
Delgado returned to the United States to face charges after previously being located in Dubai. He claims he was in the United Arab Emirates attempting to salvage the company’s operations before learning of the formal criminal complaint. Federal officials state the scheme impacted approximately 1,500 victims and involved the misappropriation of over $300 million in investor capital.
The Flight From Dubai and the Federal Surrender
Delgado broke his silence during an exclusive interview where he discussed his return from Dubai. He told reporters he felt a responsibility to come back and provide a full picture of the company’s downfall. Federal agents took him into custody shortly after his arrival on U.S. soil. The surrender marks a major turning point in a case that began when the company’s accounts were frozen earlier this year.
The former CEO maintains that his actions in Dubai were intended to protect the interests of his clients. But federal prosecutors paint a different picture. They allege Delgado used the distance to evade immediate oversight as the scale of the losses became clear. The case mirrors similar global actions, including a recent Madrid Ponzi scheme involving fake news portals and cloned websites to lure investors.
Guaranteed Returns and Missing Millions
Goliath Ventures solicited funds for what it called cryptocurrency liquidity pools. The company promised investors guaranteed monthly returns ranging from 3% to 8%. These figures are significantly higher than standard market yields. Prosecutors say the firm did not generate these profits through legitimate trading. Instead, they used money from new participants to pay off older ones while Delgado spent millions on personal luxuries.
The total amount of defrauded funds reached $328 million, as detailed in the DOJ criminal complaint filed on February 1. Federal investigators tracked the flow of money through various digital wallets and found no evidence of the low-risk trading activity promised in marketing materials. The investigation remains active as authorities look for additional co-conspirators who helped facilitate the transfers.
Legal Reckoning and Victim Recovery
Civil litigation is now mounting alongside the criminal case. The Miami-based law firm Levine Kellogg Lehman Schneider + Grossman LLP has launched an investigation into the firm’s collapse. They aim to recover assets for the 1,500 people who lost their savings in the collapse. Lawyers are focusing on third-party entities that may have helped Delgado move the funds or lent credibility to the operation.
Victims have reported losing life savings and retirement accounts. Many were attracted by the professional appearance of the Goliath Ventures platform and its promises of safety in a volatile market. The court is expected to appoint a receiver to oversee any remaining assets as the criminal trial moves forward in federal court.
Why the Goliath Ventures Collapse Signals a Shift in Crypto Litigation
The surrender of Christopher Delgado highlights a massive paradigm shift in how federal agencies pursue digital asset fraud across international borders. Unlike the early days of crypto where founders could disappear into tax havens, the cooperation between U.S. feds and international hubs like Dubai is tightening. This case serves as a warning that physical distance no longer provides the shield it once did for tech executives facing insolvency.
The involvement of high-profile class-action firms like LKLSG suggests that the focus is moving beyond just punishing the individual. The legal industry is now targeting the entire ecosystem of enablers. This means the next wave of litigation will likely hit the banks, marketing firms, and software providers that allowed the $328 million Goliath scheme to scale so quickly. For the crypto industry, the “guaranteed return” era is officially dead, replaced by a brutal cycle of federal audits and aggressive victim-led lawsuits.